Hurricane Insurance Claims | Expert Help for Florida, Texas & the Southeast
Hurricane Insurance Claims Are Tough — We Make Them Easier
Hurricane season doesn’t just bring wind and rain—it brings property damage, insurance disputes, and a mountain of paperwork. If you’re filing a hurricane insurance claim in Florida, Texas, Georgia, North Carolina, or South Carolina, you’re not alone. Thousands face this challenge every year.
Unfortunately, insurance companies often delay, deny, or underpay. Even if your policy covers hurricane damage, deductibles, exclusions, and red tape can leave you paying out-of-pocket. That’s why hiring Panther Public Adjusting can make all the difference.
Isaias forecast: what Florida Panhandle homeowners should know
Forecast checked October 7, 2026, at 4:00am CDT. The National Hurricane Center has named Tropical Storm Isaias in the Gulf. Its advisory forecasts strengthening into a hurricane by Thursday and an approach to the northern Gulf Coast Friday. The Florida Panhandle is among the areas that should monitor the forecast for wind, storm surge and heavy-rain risk.
The exact landfall location is not confirmed. NHC describes track confidence as below average. Check the latest official advisory and local emergency instructions before making safety decisions.
While it is safe, take photos of your property, save a copy of your policy and declarations page, and keep your important records somewhere you can reach if you evacuate. If damage occurs, photograph it before cleanup when safe, stop further damage with safe temporary measures, and have a public adjuster review the cause of loss and policy before deciding how to handle a claim.
For a focused checklist, see our Isaias insurance claim guide for Florida Panhandle homeowners.
Even if damage looks minor, have a public adjuster check
You do not need a missing roof or a flooded room to have your property checked after a storm. Damage can be easy to miss from the ground or during a quick walk-through. Even if you think your house came through with little damage, have a public adjuster check it.
Ask the adjuster to look for scratches on metal roofs, loose shingles or tiles, scratches on windows or stucco, and hidden water damage. These are examples of conditions to investigate, not reasons to assume every mark is new or storm-related. A careful inspection should compare the condition with the property’s history, identify what changed and document the cause.
A public adjuster can then review those findings alongside your policy and help decide whether a claim makes sense. Do not climb onto a roof or open damaged walls yourself to look for evidence.
NHC advisory: October 7, 2026, 4:00am CDT | Latest official NHC forecast
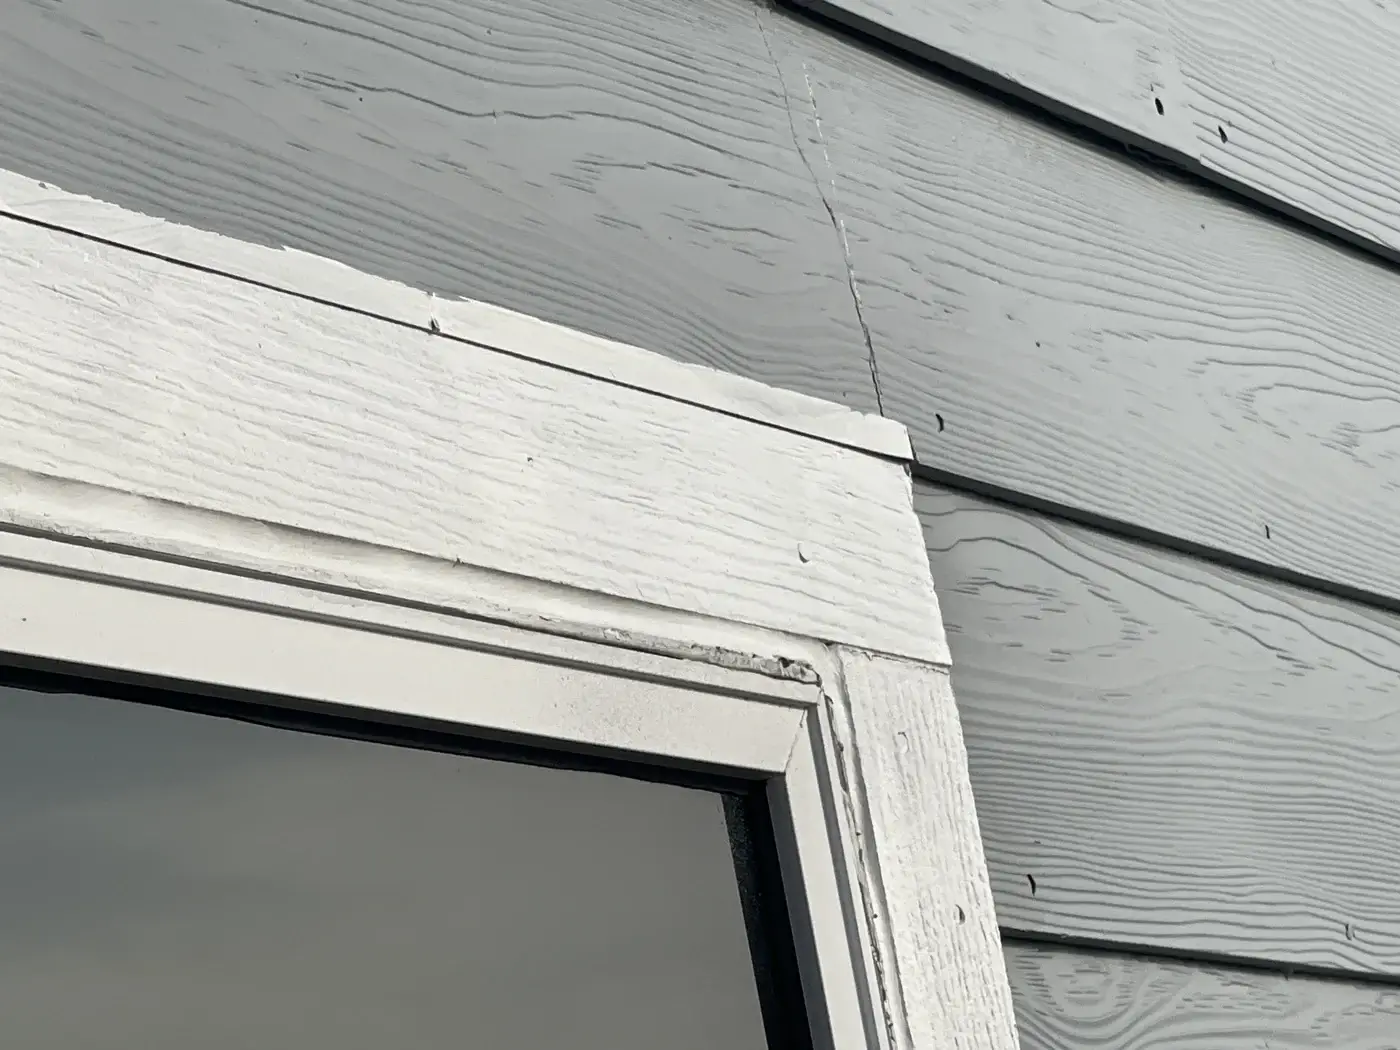
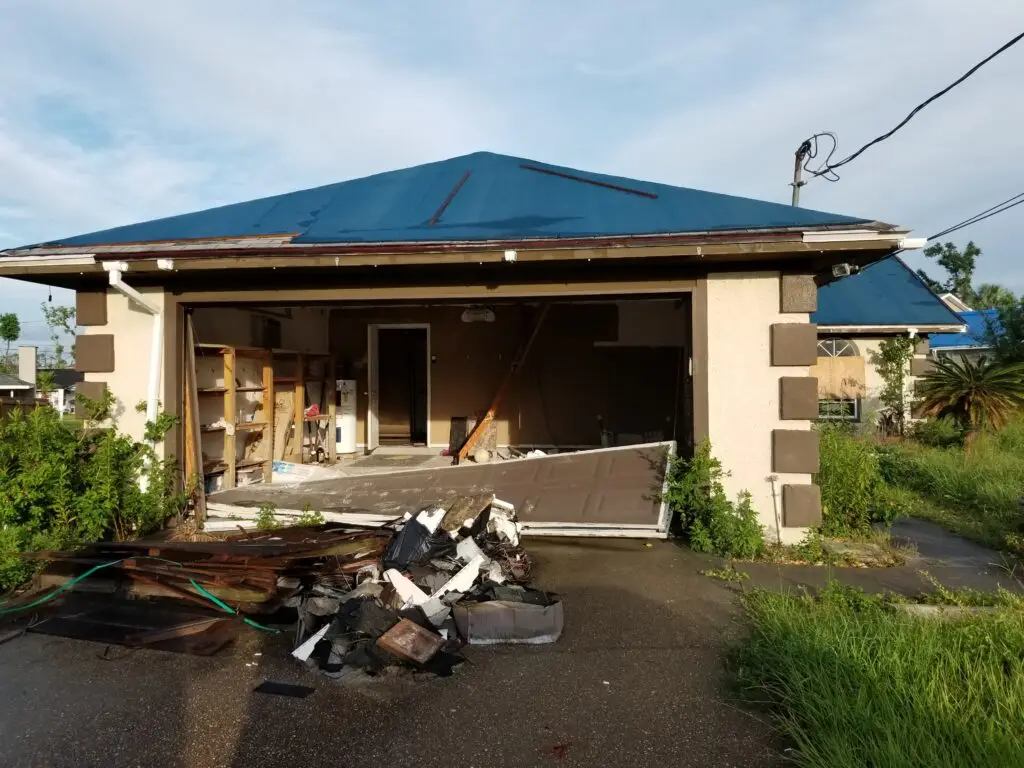
Property claim inspection example. This photograph is not Isaias damage.
Panther Public Adjusting video: Insurance Denied Your Hurricane Claim?
We hired Panther Public Adjusters to handle our claim after hurricane IAN. Even though UPC went into insolvency and the state took over the claim, we ended up getting the settlement we wanted. Jonathan worked tirelessly in doing so. 5 stars+ for Mendy and his staff!
— Kevin Lockwood
What Is a Hurricane Insurance Claim?
A hurricane insurance claim is a formal request to your insurer to pay for damages caused by a hurricane—this includes:
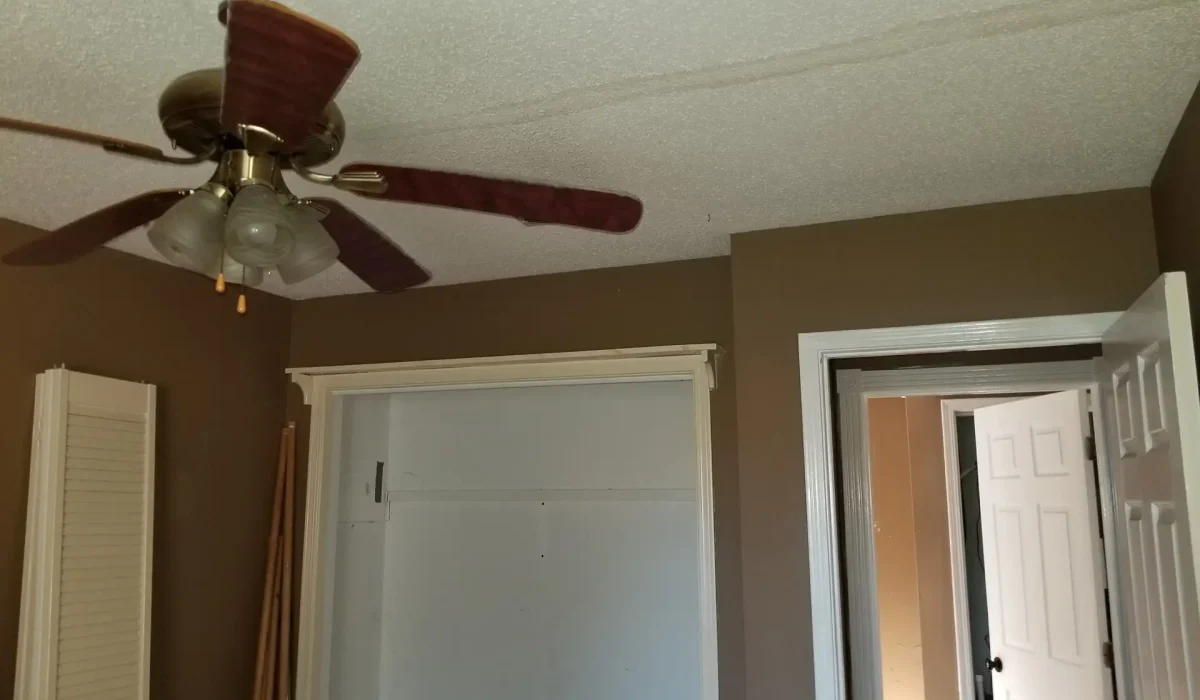
Roof damage or missing shingles
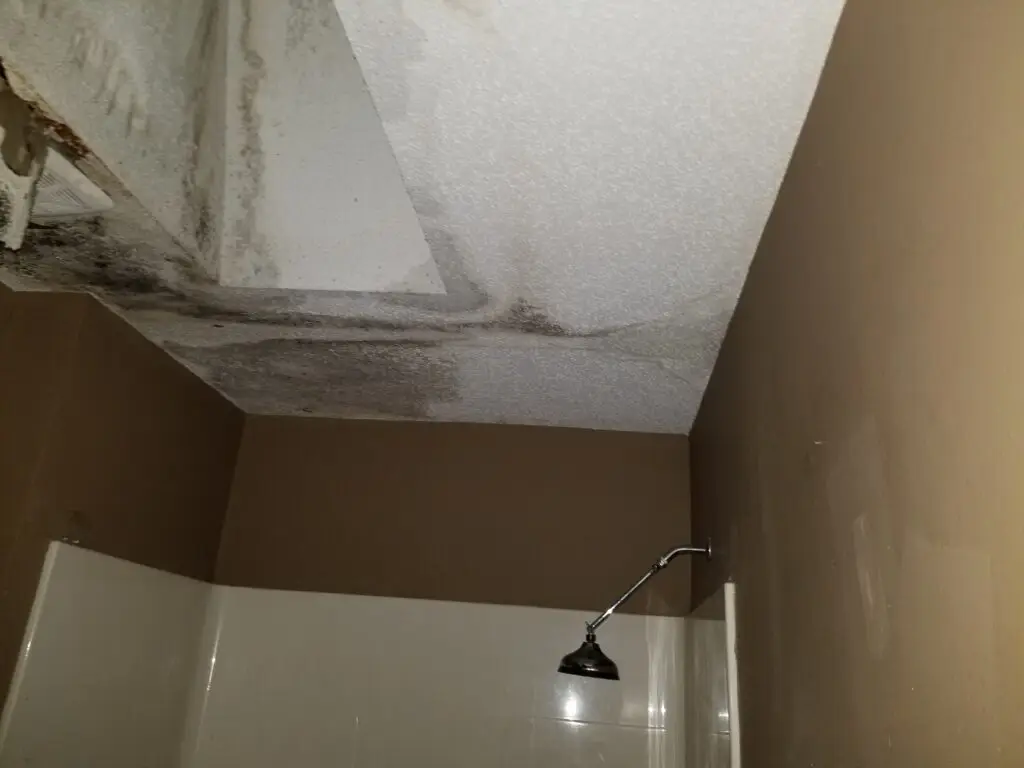
Water intrusion
Wind-blown debris damage
Loss of power systems, HVAC, or appliances
Mold growth caused by moisture
💡 Note: Flood damage is not covered by standard homeowners insurance. You’ll need a separate flood policy for water rising from the ground. This distinction often leads to confusion and denied claims.
Learn more about common pitfalls by reading how Citizens Insurance handles claim denials.
Common Hurricane Damages We Help Document
Roof & Shingle Damage – Torn shingles, structural leaks
Water Intrusion – Rain seeping into walls, ceilings, and floors
Structural Impact – Fallen trees, cracked foundations, broken windows
Electrical Issues – Damage to HVAC, lighting, and circuits
Mold Growth – Especially in humid regions like Florida and the Carolinas
Why Hurricane Insurance Claims Get Denied or Underpaid
Even legitimate claims are frequently rejected or minimized. Here’s why:
Paperwork Problems – Missing photos, reports, or receipts
Flood vs. Wind Disputes – Insurers may blame flooding to avoid paying
Missed Deadlines – Late filings can void coverage
Lowball Estimates – Carriers claim repairs are cheaper than reality
🛡️ Panther Public Adjusting protects your claim by handling documentation, deadlines, and negotiations—so you don’t have to.
How Panther Public Adjusting Helps with Hurricane Insurance Claims
We’ve worked thousands of hurricane claims. Here’s how we help:
Inspect the Damage – We uncover both obvious and hidden losses
Document Everything – Photos, videos, reports, receipts
Interpret Your Policy – We identify what coverage applies
Handle the Carrier – We push back on low offers and delays
Maximize Your Payout – We fight for every dollar you’re owed
Check out this family’s story of rebuilding after their home was destroyed.
Local Knowledge in Every State We Serve
Florida:
We navigate complex deductibles and timeframes. Our team moves quickly to document mold, roof, and structural damage.
Texas:
We help homeowners and business owners with private insurers and state-run plans like TWIA (Texas Windstorm Insurance Association).
Georgia, North Carolina, South Carolina:
We know the state-specific laws and how to respond when insurers drag their feet.
Real Hurricane Claim Success Stories
🏠 Parrish, FL
The homeowner called us right after Hurricane Milton. While they had a notoriously difficult insurance carrier, we resolved the claim in record time for over $140,000
🏢 Cape Coral, FL
After Hurricane Ian, an insurer offered $19,000 for a roof and interior repairs. Panther stepped in and settled for $91,000—nearly 5x more.
🛏️ Beaumont, TX
Our client was denied for “flood exclusion.” We proved wind-driven water was the true cause and recovered $58,000.
5 Steps After Hurricane Damage
- Put safety first. Follow evacuation and re-entry instructions. Do not enter an unsafe building or climb onto a damaged roof to collect evidence.
- Photograph damage as soon as it is safe. Capture wide views and close-ups of affected rooms, roof areas visible from the ground, belongings and water entry points.
- Identify the cause and prevent further damage. Bring in a qualified professional when needed. Keep receipts and photos of temporary work, such as safe tarping or water removal.
- Have a public adjuster check, even if the damage looks minor. Ask about scratches on metal roofs, loose shingles or tiles, scratches on windows or stucco, and hidden water damage. Review the cause of loss and policy together before deciding whether a claim makes sense.
- Let Panther Public Adjusting help with documentation and insurer communication. Call 833-PANTHER to discuss your damage and the next steps.
State-Specific Hurricane Claim Rules at a Glance
State | Deadline Notes & Claim Tips |
|---|---|
| Florida |
Insurers must respond in 14 days, decide in 60. But delays are common—especially after major storms. |
Texas
| Check if your policy is with TWIA. Windstorm-only policies have unique procedures. |
| Georgia & Carolinas | Filing timeframes vary. We stay on top of each state’s insurance code so you don’t have to. |
Start Your Hurricane Insurance Claim Review Now
Filing a hurricane insurance claim can be exhausting—unless you have a seasoned public adjuster fighting for you. Let Panther PA protect your payout and make sure your recovery is fair and complete.
📧 Email: Claims@PantherPA.com
📞 Call: 833-726-8437
📝 Schedule Your Free Claim Review »
Explore More Hurricane Recovery Resources:
Areas we serve in Florida: Miami | Miami Beach | North Miami Beach | Aventura | Hollywood | Hallandale Beach | Fort Lauderdale | Pompano Beach | Pembroke Pines | Coral Springs | Boca Raton | Doral | Hialeah
FAQs About Hurricane Claims
How long do I have to file an insurance claim after a hurricane?
The timeframe varies by state and insurance provider, but generally, you should file your claim as soon as possible—ideally within a few days of the storm. In Florida, for example, there’s a statute of limitations that gives you up to one year from the date of the hurricane to file a claim, but it’s always better to act quickly to avoid disputes or missed deadlines.
How do I file an insurance claim after a hurricane?
Start with safety, then photograph the damage and arrange safe temporary protection. Even if you do not think there was much damage, have a public adjuster check the property and review your policy and the cause of loss before deciding whether to file. If Panther Public Adjusting takes on your claim, we can help document the loss and handle communication with the insurance company. Keep copies of your photos, receipts, reports and correspondence together.
Can an insurance company drop you after a hurricane claim?
Unfortunately, some insurance companies may not want to renew a policy after a hurricane claim, especially if the region is deemed high-risk. However, this varies significantly by state. For instance, in Florida, state law prohibits insurers from dropping homeowners solely for filing a claim caused by an “act of God,” such as a hurricane. Each case is unique, and non-renewal must still comply with state-specific regulations. If you’ve received a notice, consult with a public adjuster or insurance attorney to understand your rights and protections.
When should I get help after hurricane damage?
As soon as it is safe to assess the property, even if the damage looks minor. A public adjuster can check for less noticeable damage, identify the cause of loss, review the policy and work out the next steps. Policy notice requirements and claim deadlines need to be checked for your loss; do not wait for every repair estimate before seeking help.
What should I do if my hurricane claim is denied?
If your claim is denied, don’t panic. Review the denial letter carefully and compare it with your policy. Often, denials are due to technicalities, incomplete documentation, or misinterpretation of the damage. A public adjuster can help reassess your claim, gather additional evidence, and dispute the insurer’s decision if necessary.
What types of damage are typically covered by hurricane insurance?
Most hurricane insurance policies cover wind damage, roof damage, broken windows, water intrusion from rain entering through storm-created openings, and more. However, flooding from storm surge is usually excluded and requires separate flood insurance. Check your policy details or consult a professional to confirm your coverage.
Can I reopen a hurricane insurance claim?
Yes, in many cases you can reopen a claim if new damage is discovered or if you believe you were underpaid. Most states allow supplemental claims, but there are deadlines—often 12 to 24 months post-storm. Documentation is crucial, and a public adjuster can assist with the process.